Common Personal Finance Mistakes to Avoid
Managing money is not always about earning more. Sometimes, small financial habits can make a surprisingly big difference to your long-term financial situation.
You might have a decent income and still struggle to save. Why? Overspending, poorly planned debt, forgotten subscriptions, and a lack of emergency savings can all add up.
The good news is that many common personal finance mistakes are avoidable.
Not Having a Realistic Budget
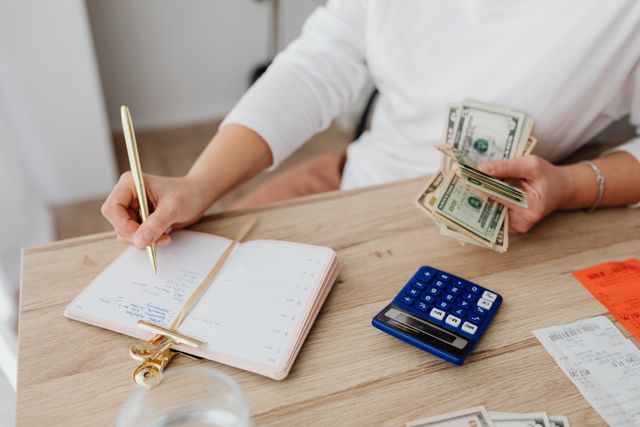
A budget is more than a list of bills. It gives you a clearer picture of where your money goes each month.
Without one, it's easy to underestimate everyday spending on food, entertainment, subscriptions, transportation, or online purchases.
Start by tracking your income and regular expenses. Then separate essential spending from discretionary purchases.
You don't need a complicated spreadsheet. Even a simple monthly overview can reveal patterns you might otherwise miss.
Ignoring an Emergency Fund
Unexpected expenses are part of life. A broken appliance, urgent travel, car repair, or temporary loss of income can put pressure on your finances.
An emergency fund provides a financial buffer for these situations.
How much you need depends on your circumstances, income stability, expenses, and other factors. The important point is to build savings before an emergency happens rather than trying to find money afterward.
Relying Too Much on Credit
Credit cards and loans can be useful financial tools, but borrowing can become expensive when balances are carried over and interest accumulates.
Before taking on new debt, consider the total cost rather than focusing only on the monthly payment.
|
Common Mistake |
Potential Problem |
Better Habit |
|
No budget |
Unclear spending patterns |
Track monthly income and expenses |
|
No emergency savings |
Difficulty handling unexpected costs |
Build a cash reserve |
|
Minimum debt payments |
Interest can accumulate |
Pay more when possible |
|
Ignoring fees |
Small costs add up |
Review account and service fees |
|
No financial goals |
Saving lacks direction |
Set specific goals |
Paying Only the Minimum on Debt
Making the minimum required payment can keep an account current, but it may also mean paying interest for a much longer period.
When possible, understand how interest works and prioritize expensive debt according to your financial situation.
Even small additional payments can change how quickly a balance is reduced.
Forgetting About Recurring Expenses
That streaming service you rarely use? The subscription you forgot to cancel? The account fee you barely notice?
Recurring expenses can quietly consume part of your income month after month.
Review your bank and card statements regularly. Cancel services you no longer need and check whether there are lower-cost alternatives for expenses you use frequently.
Not Setting Financial Goals
"Save more money" is a good intention, but it is not a very specific goal.
Instead, give your savings a purpose. You might be saving for an emergency fund, education, a home, travel, or retirement.
Clear goals make it easier to decide how much to save and track your progress.
Chasing Quick Investment Returns
Investing can play an important role in long-term financial planning, but chasing investments simply because they are trending can expose you to risks you may not fully understand.
Before investing, consider your objectives, time horizon, risk tolerance, and the possibility of losing money.
Diversification can also help reduce reliance on the performance of a single investment.
Neglecting Retirement Planning
Retirement can feel far away, especially when you're focused on today's expenses. But delaying retirement planning can reduce the time available for savings and investment growth.
Even if you cannot contribute a large amount immediately, starting with an amount that fits your budget can help establish a long-term habit.
Not Reviewing Your Financial Situation
Your finances change over time. Your income, expenses, debt, goals, and family circumstances may all look different a year from now.
Set aside time periodically to review your budget, savings, debt, insurance, subscriptions, and financial goals.
Think of it as a financial health check—not something you do only when there is a problem.
Conclusion
Good personal finance is rarely about making one perfect decision. It is usually about avoiding repeated mistakes and building sustainable habits.
Create a realistic budget, maintain an emergency reserve, understand your debt, control recurring expenses, set clear goals, and review your finances regularly. Small improvements can become meaningful over time.
Frequently Asked Questions


Was This Article Helpful?
Click on a star to rate it!
Thank you for your vote!

Average Rating: 5/5 Votes: 1
Be the first to rate this post!
Expert in backend development and database architecture. Specializes in building, optimizing, and maintaining scalable PHP applications, designing efficient database structures, and ensuring data integrity and performance. Experienced in working with relational databases, writing optimized queries, and integrating backend systems with APIs and business logic to support reliable, high-performance web solutions.
View LinkedIn ProfileLatest Posts
Common Personal Finance Mistakes to Avoid
SEO Content Strategies That Rank Higher
How Economic Trends Influence Investment Markets